
Automated controls
Three-way match and duplicate detection catch errors before they reach payment, not after.
Three-way match, policy-aware approvals and audit-ready trails on every transaction - so finance gets clean data and fewer surprises at close, without adding headcount.
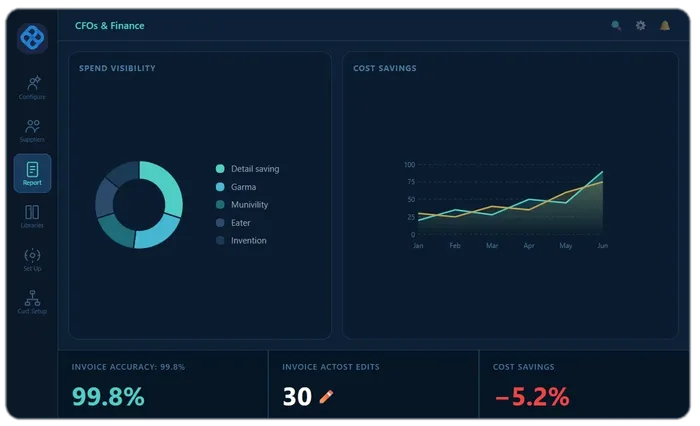
Three-way match and duplicate detection catch errors before they reach payment, not after.
Every approval, match and exception is logged - no scrambling before statutory audit.
Real-time visibility into committed spend and payables position, not month-end reconciliation.
The finance objection to procurement software is rarely about procurement. It is that the savings number arriving from procurement cannot be reconciled to anything in the ledger. A figure is reported, finance cannot trace it to transactions, and the two functions end up negotiating about the number rather than acting on it.
That gap is structural, not political. A saving negotiated in a sourcing event only becomes a realized saving if the requisition routes to the resulting contract, the purchase order carries the contracted price, and the invoice is matched before payment. When those steps run in disconnected systems, the chain from negotiation to ledger has no single owner, and the reported figure drifts from the realized one with nobody able to say precisely where.
The second accountability is defensibility. When an auditor asks why a supplier was chosen or who approved a payment, the answer has to be reconstructable from the record rather than from memory. A trail that spans four systems is a project to assemble; a trail in one is a query.
Both are the reason controls belong inside the transaction flow rather than as a review step after it. Three-way match, policy-aware approval routing and duplicate detection prevent the exception rather than reporting it, which is also what keeps the close from depending on chasing.
Baselines agreed once with finance and reused, so the same category is not measured three ways in three reviews. Spend analytics for the consolidated view across entities and ERPs, invoice automation for the matching and exception path, and the ERP as the financial system of record.
What it does not do. It cannot make a savings figure credible if the baseline was never agreed. That conversation happens before the sourcing event, not after the number is reported.
Procurement affects several numbers finance owns outright. These are the ones where the link is direct enough to be worth tracking.
| What finance owns | What makes it hard | What moves it |
|---|---|---|
| Realized versus negotiated savings | A saving agreed in a sourcing event is a forecast until the invoice matches it. Most reported savings are never reconciled. | Sourcing tied to invoice matching |
| Committed spend visibility | Commitments made at PO are invisible to finance until the invoice lands, so the forecast is always behind. | Procure-to-pay and spend analytics |
| Invoice exception rate | Exceptions are handled by people, and the cost sits in AP headcount rather than in any procurement metric. | Invoice automation |
| Off-contract and maverick spend | Buying outside an agreed contract looks identical to compliant spend in the ledger. | Intake and source-to-contract |
| Audit and control evidence | Demonstrating who approved what, and on what authority, usually means reconstructing it after the fact. | Approval workflows |
The gap between a savings number and a P&L movement is where finance loses trust in procurement. This is how the two are reconciled.